How Much Equity Do You Need to Move Up in Richmond, VA?
What Richmond homeowners should know before making their next move
If you’ve owned your home for a few years, you may have more equity than you realize.
And if you’ve started thinking about a bigger house, a different neighborhood, a better school location, more yard space—or simply a home that fits your life a little better—the equity you’ve built could be an important part of making that next move happen.
One of the questions I hear from homeowners is: “How much equity do I actually need to move up?”
There isn’t one magic number. It depends on the value of your current home, what you still owe, the price of the home you want to buy, and how much cash you want to put toward your next purchase.
But understanding your numbers can give you a much clearer picture of what your options look like.
First: What is home equity?
Home equity is simply the difference between what your home is worth and what you still owe on your mortgage.
For example, if your Richmond-area home is worth $600,000 and your remaining mortgage balance is $350,000, you have approximately $250,000 in equity.
That doesn't mean you would necessarily walk away from a sale with $250,000 in your pocket. You still have to account for selling expenses, your mortgage payoff and any other costs associated with the transaction.
But that equity can become a significant piece of your next move.
How much equity do you need to move up?
The answer depends on what you're buying.
Let's say your current home is worth $600,000 and you owe $350,000.
You have approximately $250,000 in gross equity.
If you sell, some of that money will go toward the costs of selling your current home. What's left is your approximate net proceeds.
Now imagine you're looking at a $750,000 home.
You don't necessarily need to come up with a $750,000 down payment. Your existing equity can potentially provide a substantial portion of the funds you'll use for the next purchase.
That's why the conversation shouldn't start with: “Do I have enough equity to move?” A better question is: “What would my current home likely sell for, what would I net from the sale, and how does that compare with what I want to buy next?”
Those numbers tell you much more.
What does moving up actually cost?
When homeowners think about moving up, they often focus on the difference between the two home prices.
For example:
Current home: $600,000
Next home: $750,000
Difference: $150,000
But that's not necessarily the amount of cash you'll need.
Your actual calculation may look more like:
Estimated sale price of current home
− Mortgage payoff
− Selling expenses
= Estimated net proceeds
Then:
Estimated net proceeds
-
Cash you're comfortable using
-
Potential financing
= Buying power for your next home
There are also costs associated with purchasing your next home, so it's important to look at the entire picture rather than simply comparing the two purchase prices.
This is where talking through the numbers before you put your house on the market can make a big difference.
You may not need 20% down
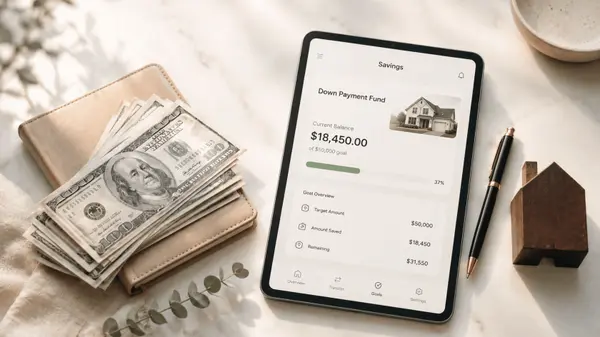
One misconception I hear from homeowners is that they need to have 20% saved for the next house before they can move. That's not necessarily the case. The right down payment depends on your loan program, financial situation, goals and what you and your lender decide makes sense. For some move-up buyers, putting every dollar of available equity into the next house isn't the best strategy. You may want to keep some cash available for moving expenses, repairs, furnishings, renovations or simply a financial cushion. Your lender can help you determine what financing options make sense, while your Realtor can help you understand the real estate side of the equation.
What if you need to sell your current home first?
This is one of the biggest questions for Richmond-area move-up buyers. You may have plenty of equity in your current home, but that doesn't necessarily mean you have a large amount of cash sitting in the bank. If most of your available funds are tied up in your current home, the timing of your sale and purchase becomes important. There are several ways buyers approach this, depending on their circumstances.
You might:
-
Sell your current home before purchasing
-
Make an offer on your next home that is contingent on the sale of your current home
-
Sell first and arrange temporary housing if necessary
-
Explore financing options with your lender that may allow for more flexibility
There isn't one right approach for everyone. The important part is knowing your options before you start seriously shopping.
What if your home needs work?
This is another reason I recommend getting a realistic idea of your home's value before making a decision. You might look around your house and think:
“There's no way we're getting enough out of this house to move.”
But you may be surprised. Or you may discover that your home would benefit from a few strategic updates before going on the market. That doesn't mean you need to completely renovate your kitchen or tackle every project on your list. Sometimes it's a matter of determining which improvements are worth doing, which aren't, and what your home could realistically sell for in its current condition. And sometimes the answer is simply: don't spend the money.
That's information worth having before you start writing checks.
Richmond's move-up market isn't just about price
When I talk with homeowners about moving up in the Richmond area, the conversation is rarely just about getting a bigger house. Often, the reason for the move is lifestyle.
Maybe you're looking for:
-
More bedrooms
-
A larger yard
-
A home office
-
A different school area
-
A neighborhood with more amenities
-
Less maintenance
-
A shorter commute
-
More entertaining space
-
A home that better fits where your family is now
Your next move should make sense for your life—not just your square footage. That's why I like to start with the bigger picture and work backward from there.
A simple example
Let's say you've owned your home for eight years.
It's now worth approximately $650,000, and your mortgage balance is $325,000.
That gives you roughly $325,000 in gross equity.
After accounting for the costs associated with selling, your actual proceeds would be lower—but potentially still substantial.
Now you're considering a home in the $800,000 range.
At first glance, that $150,000 price difference might seem like the biggest hurdle.
But once you know your estimated net proceeds and talk with a lender about financing, you can determine whether the move is realistic, what your monthly payment might look like, and how much cash you would want to keep in reserve.
That's a much better place to make a decision from than simply guessing.
So, do you have enough equity to move up?
Maybe. And you don't have to be ready to sell tomorrow to find out.
If you're a Richmond, Midlothian, Chesterfield or Henrico homeowner who's been wondering whether your current home has put you in a position to move up, I'd start with three numbers:
1. What could your current home realistically sell for?
Not what Zillow says. Not what your neighbor's house sold for three years ago. A realistic estimate based on the current market and comparable homes.
2. What do you still owe?
Your current mortgage balance gives you a starting point for understanding your equity.
3. What would you want to buy next?
This doesn't have to be an exact address. Even having a general idea—$700K, $800K, $1M, etc.—helps put the numbers into perspective.
Once you have those three pieces, you can start having a much more productive conversation with your Realtor and lender.
Your next move may be closer than you think.
You don't need to put your house on the market just because you're curious about what it could be worth. And you certainly don't need to start touring houses before you know what you're comfortable spending. Sometimes the smartest first step is simply understanding your options.
If you're curious about what your current home could be worth, how much equity you may have, or what a move-up purchase could look like in the Richmond area, I'd be happy to help you run through the numbers.
No pressure to move. Just a better idea of what's possible.
Categories
Recent Posts